Key Takeaways
- The S&P 500 posts a slightly negative month
- Inflation may be moderating
- Oil prices declined sharply
- New Fed Chair takes his seat
Stock Market Recap
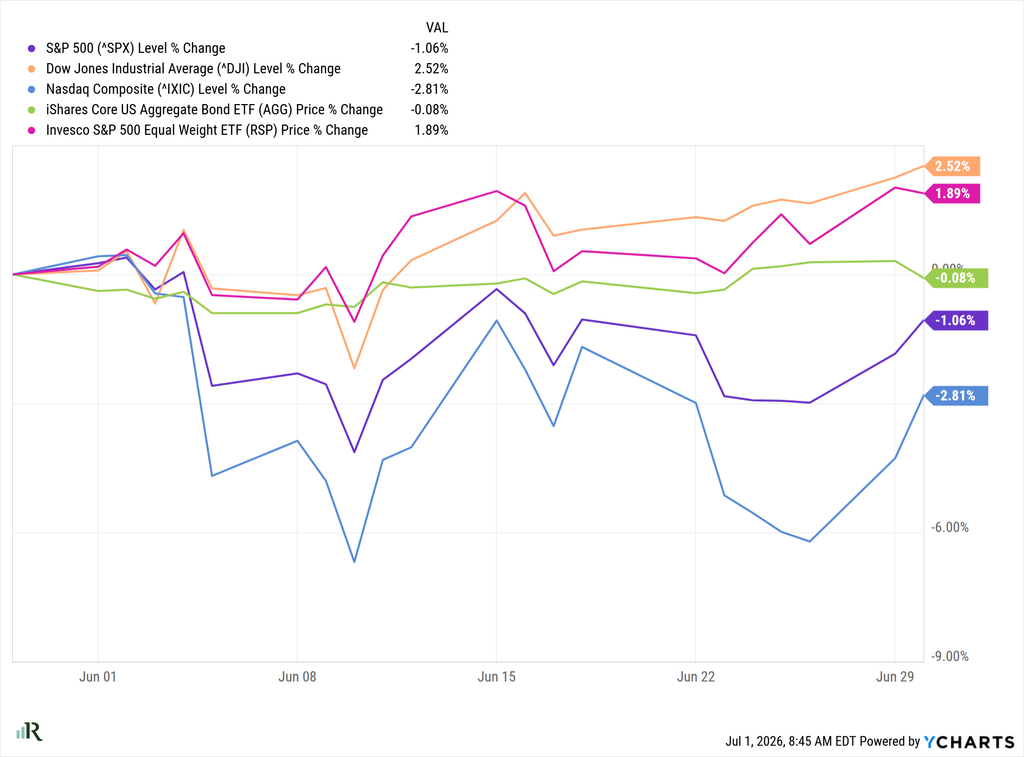
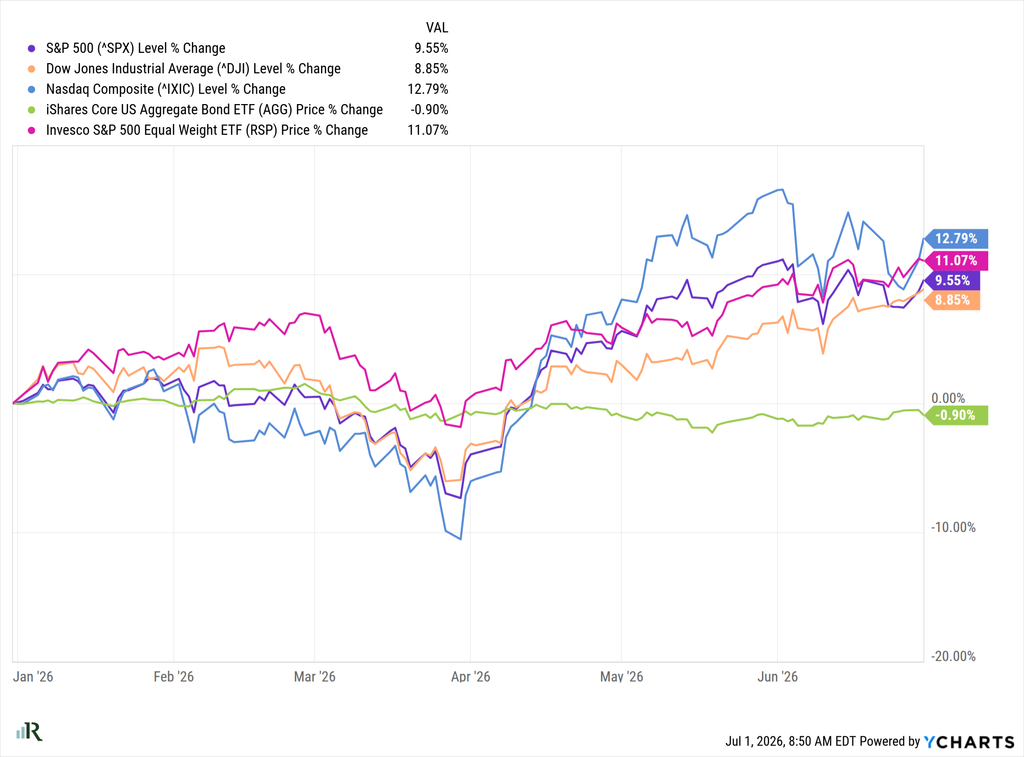
The S&P 500 declined just over 1% in June, as markets experienced elevated volatility, particularly within the artificial intelligence (AI) and semiconductor sectors. Despite the monthly pullback, the index delivered a strong first half of the year, gaining 9.55%.
The “Magnificent Seven” stocks (Nvidia, Apple, Microsoft, Alphabet, Amazon, Meta, and Tesla) experienced a particularly challenging month, with several declining more than10%. As a result, portfolios heavily concentrated in these names generally underperformed the broader S&P 500. The technology-heavy Nasdaq Composite also struggled, falling 2.81% as these companies represent a significant portion of the index.
In contrast, broader market participation was evident as the S&P 500 Equal Weight Index gained 1.89% during the month. This divergence highlights the benefits of maintaining diversified exposure rather than concentrating heavily in a single sector or group of stocks.
A major market event during the month was the long-awaited SpaceX initial public offering on June 12. Upon its debut, SpaceX immediately became one of the ten largest publicly traded companies by market capitalization, approaching the size of Amazon—an extraordinary achievement. We believe the IPO also contributed to short-term market volatility, as capital appeared to rotate into the new offering, putting additional pressure on several large-cap technology stocks, including members of the Magnificent Seven, both before and after the IPO.
Inflation
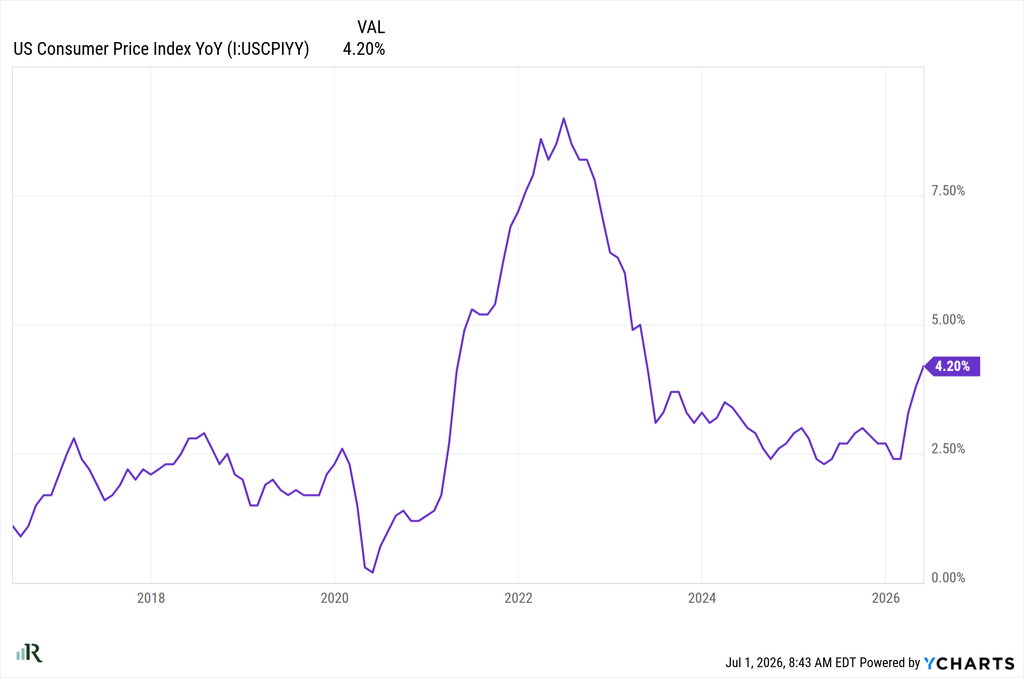
Inflation, as measured by the Consumer Price Index (CPI), has risen to its highest level since late 2024. While that may sound concerning, there are encouraging signs that inflationary pressures could begin to ease in the coming months. The recent decline in oil prices, along with softer pricing across several other commodities, should help moderate inflation if these trends continue.
As always, we’ll continue to monitor inflation closely, as it remains an important factor influencing interest rates, consumer spending, and overall market performance.
Oil Prices
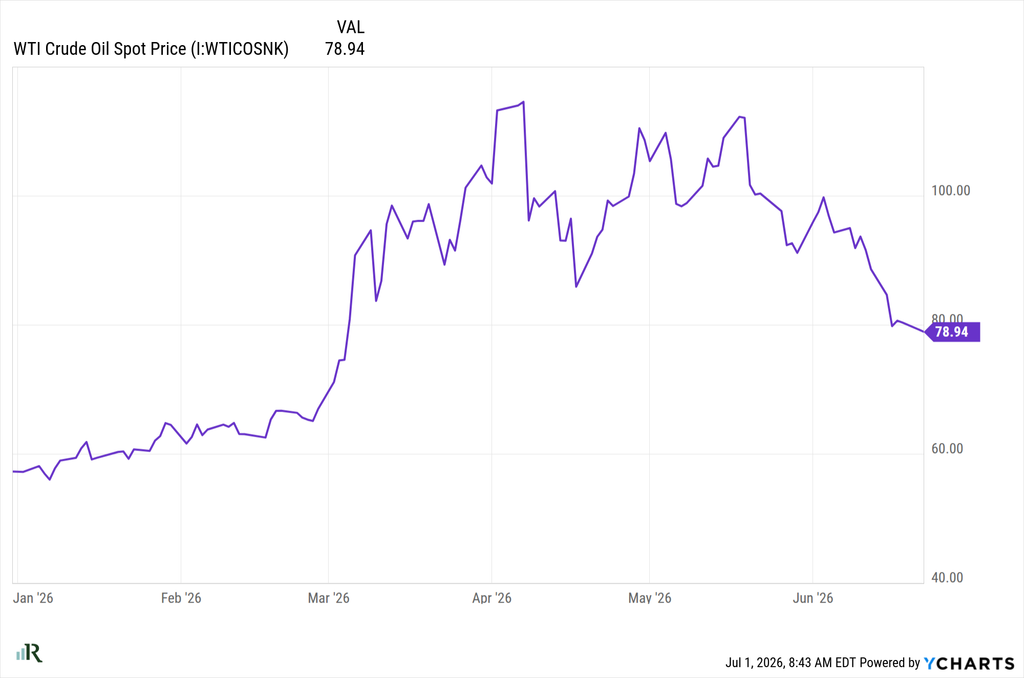
Oil prices declined sharply during the month, falling from highs above $115 per barrel to just over $78. Much of the decline followed the announcement of a ceasefire between the United States and Iran, along with continued diplomatic efforts aimed at reaching a longer-term resolution to the conflict.
The speed of the decline has been notable, but lower oil prices are welcome news for consumers and could help ease inflationary pressures in the months ahead. Our outlook remains largely unchanged: as long as the ceasefire holds and negotiations continue to move in a positive direction, oil prices are likely to remain relatively contained.
That said, geopolitical events can change quickly. Until a lasting agreement is reached, the potential for renewed tensions remains, and with it, the possibility of continued volatility in energy prices.
New Fed Chair & Interest Rates
Attention has now shifted to the Federal Reserve following the new Chair’s first Federal Open Market Committee (FOMC) meeting on June 16-17. Leading up to the meeting, many investors expected the new Chair to take a more “dovish” approach— meaning agreater willingness to lower interest rates if economic conditions warranted.
Instead, the Committee’s comments were more cautious than many had anticipated, suggesting that policymakers remain focused on inflation risks. As a result, the outlook for interest rates has become somewhat less certain. Current market expectations indicate there is a meaningful possibility of an interest rate increase later this year, with September viewed as one of the more likely meetings for such a move.
Our view remains that patience is the most appropriate course of action. With energy prices having retreated significantly and other inflationary pressures showing signs of easing, allowing time for these developments to work their way through the economy may prove to be the most prudent approach before making further changes to monetary policy.
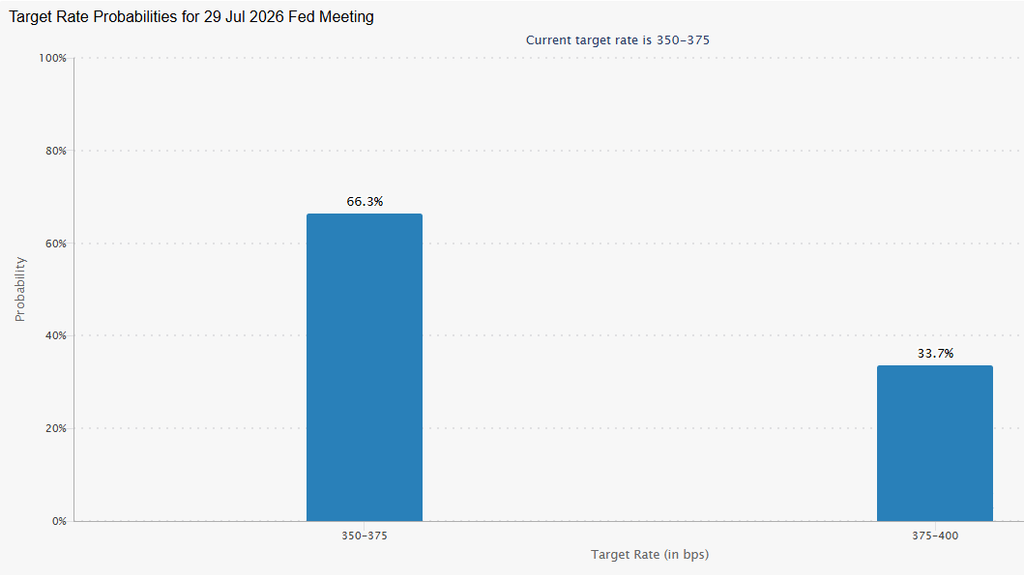
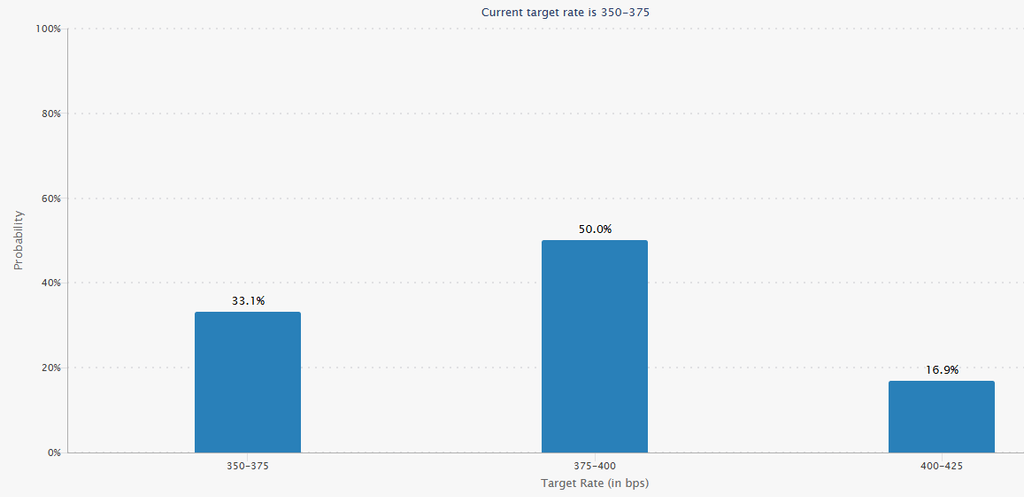
Source: CME FedWatch Tool – CME Group
Information as of 7.10.26
Securities offered by Registered Representatives through Private Client Services, Member FINRA/SIPC. Advisory products and services offered by Investment Advisory Representatives through Rockport Wealth LLC, a Registered Investment Advisor. Private Client Services and Rockport Wealth LLC are unaffiliated entities. The opinions contained herein are that of the authors not necessarily that of Private Client Services LLC and there should not be any guarantees assumed from the information presented.
Investments in securities do not offer a fixed rate of return. Principal yield and/or share price will fluctuate with changes in market conditions, and when sold or rendered, you may receive more or less than originally invested. No system of financial planning strategy can guarantee future results. Investors cannot directly invest in indices. Past performance does not guarantee future results. The performance numbers we mention are indexes. If you’re a client, we manage a custom portfolio for your particular situation and the performance will be different. You cannot invest directly in an index. Investing in an index fund involves fees and will reduce your overall return compared to the index.
Charts produced at yCharts.com
Rockport Wealth Advisors is a DBA of Rockport Wealth, LLC, a fee-based Registered Investment Adviser (RIA) registered with the Securities and Exchange Commission and offering a full range of professional services. The scope of any financial planning and/or consulting services to be provided depends upon the needs of the client and the terms of the engagement. Please see our CRS & ADV disclosure documents for more information about our business.